Free · no signup · nothing is sent to us
Debt Snowball vs Avalanche Calculator
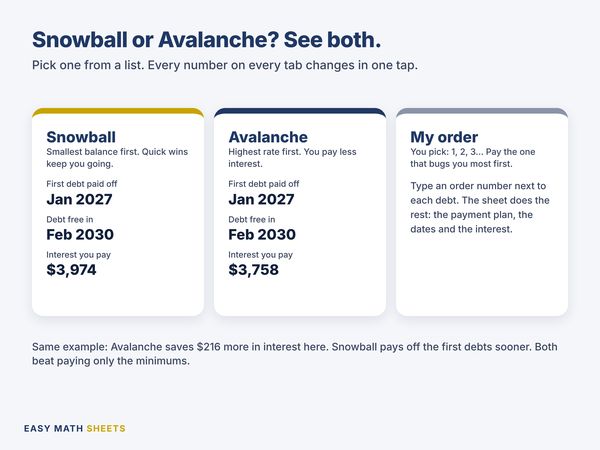
Type your debts and the extra money you can pay each month. See the snowball and the avalanche side by side: the order, when each debt is gone, and what each one costs in interest.
Budget CalculatorChristmas Budget CalculatorSnowball vs Avalanche
Snowball vs avalanche
Type at least one debt: its balance, yearly rate and minimum payment.
| What | Snowballsmallest first | Avalanchehighest rate first |
|---|---|---|
| Order | ||
| First debt gone | — | — |
| Debt free | — | — |
| Total interest | — | — |
| Debt | Snowball | Avalanche |
|---|---|---|
| Debt 1 | — | — |
| Debt 2 | — | — |
| Debt 3 | — | — |
| Debt 4 | — | — |
| Debt 5 | — | — |
| You owe now | — | |
What you still owe, month by month
| Month | Snowball | Avalanche | Debts left |
|---|
How the math works: each month, interest is the balance × the yearly rate ÷ 12. Every debt gets its minimum. The extra goes to one debt at a time. When a debt is gone, its minimum joins the extra. Banks count interest by the day, so real bills will be a few dollars off. Look at the gap between the two. A planning tool, not financial advice.
How it works
- Type your debts. For each one: what you owe, the yearly rate and the minimum payment. Up to 5 debts.
- Type your extra money. This is what you can pay each month on top of all the minimums.
- Read the answer. The calculator runs both plans, month by month, and puts them side by side.
- Debt snowball: the extra money goes to the smallest balance first.
- Debt avalanche: the extra money goes to the highest rate first.
In both plans, every debt gets its minimum each month. When a debt is gone, its minimum joins the extra money and goes to the next debt.
The example numbers are Example B from our guide: a $1,900 dentist plan at 0%, a $7,400 car loan at 7.5% and an $11,500 credit card at 27.24%. Minimums add up to $630. With $200 extra, $830 goes to debt each month.
The snowball pays off the dentist plan in month 7 and is debt free in month 34, with $7,320 in interest. The avalanche is debt free in month 33, with $5,798 in interest.
So the avalanche saves $1,521. The snowball gets you the first win 17 months sooner.
Want the whole story? Read our guide: Debt snowball vs avalanche: which one pays off faster? It shows when the gap is $66, when it is $1,521, and a simple rule for the lists in between.
Questions people ask
Which one should I pick? Look at the gap. If it is small, the snowball's early win may be worth it. People who close a debt early are more likely to stick with the plan. If the gap is big, the avalanche keeps that money in your pocket.
Why is my bank's number a little different? Banks count interest by the day, and some months are longer. We use the balance times the rate, divided by 12. So a real bill will be a few dollars off. The gap between the two plans is what to look at.
It says my debt never ends. Why? Your payments do not cover the interest. Each month the interest adds more than you pay, so the balance never goes down. Check the minimum on your bill, or add extra money.
What if two debts have the same rate? The avalanche pays the smaller one first. It costs the same, and you get the win sooner. If two debts have the same balance, the snowball pays the higher rate first.
What about a 0% plan? Type 0 as the rate. A 0% debt often pays itself off with its own minimum. Check when the 0% ends: if the rate goes up later, the order may change.
Is my data saved or sent? No. The math runs on your phone or computer. Nothing is saved. Close the page and it goes back to the example. It is a planning tool, not financial advice.
More free help
- Need to find your extra money first? Try the free budget calculator. Extra debt payments come out of the savings part.
- Want a plan for every bill and payday? See the Monthly Budget Planner.
The calculator shows the plan. The sheet keeps you on it.
Want a plan you can follow every month until you are debt free?
The Debt Payoff Planner spreadsheet does that: up to 15 debts, Snowball or Avalanche, what to pay on each debt this month, and progress bars as they shrink. $3.98, one time.